
Table of Contents
Impact of Interest Rate Hike in the UAE’s Banking Sector
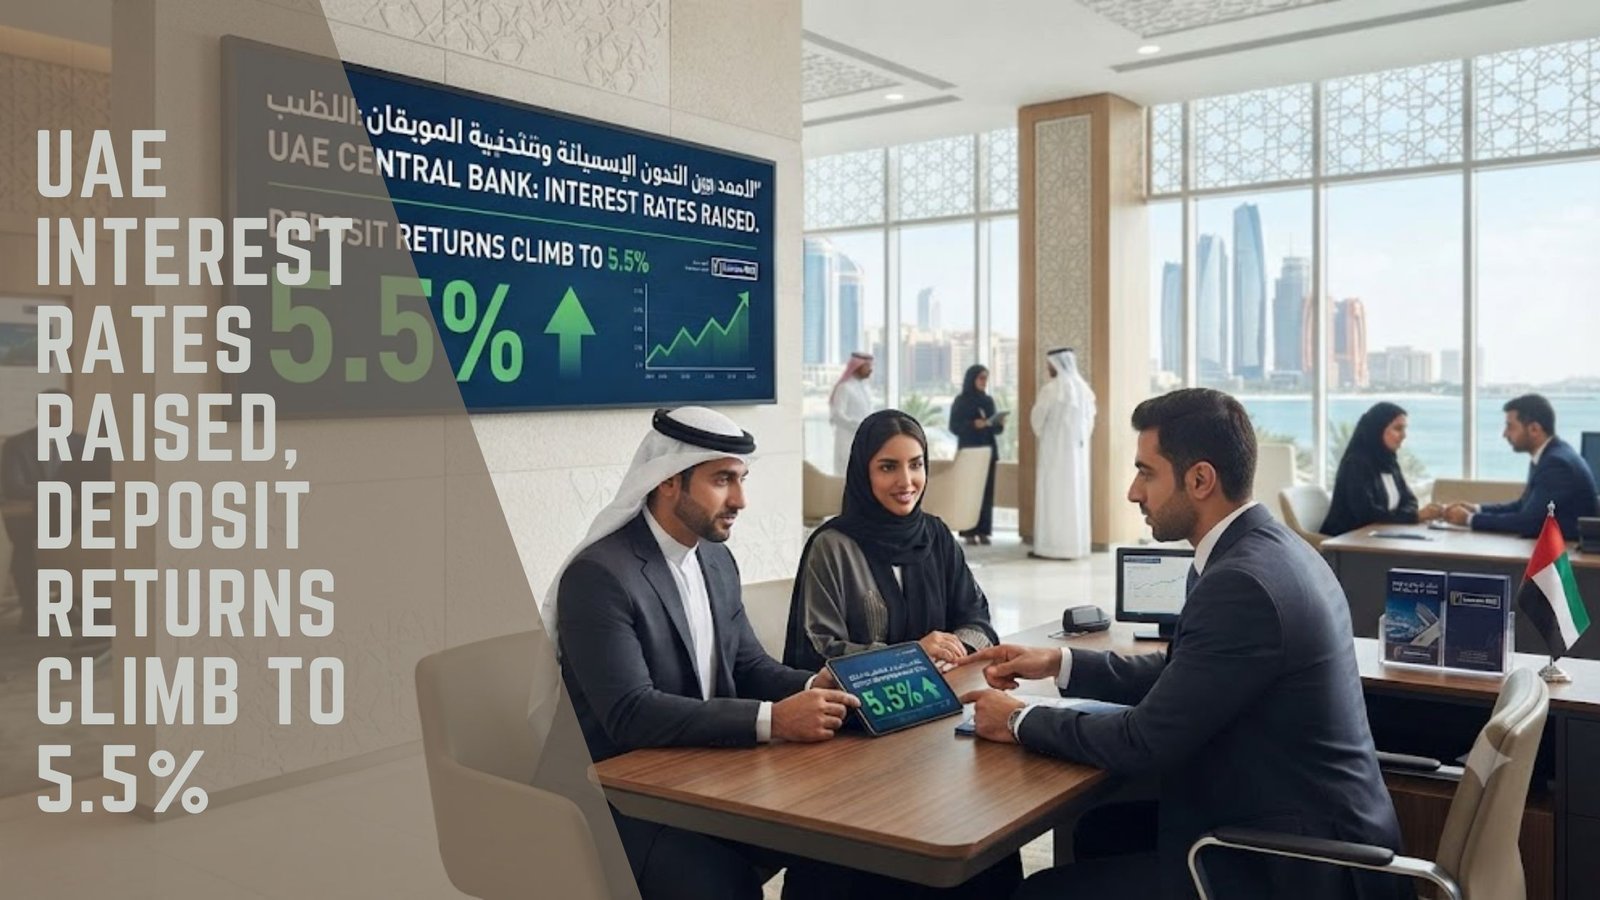
The United Arab Emirates’ banking sector is witnessing significant changes following the Central Bank’s decision to increase the base interest rate by 25 basis points. This move, reflecting a similar action by the US Federal Reserve due to the dirham’s peg to the dollar, marks the first rate hike in over three years.
Deposit Returns Surge
The most immediate impact of the rate increase is observable in the returns on deposits. As of last Saturday, deposit rates have risen to a range of 4.5% to 5.5%, depending on the duration of the deposit. This adjustment presents an opportunity for savers to benefit from higher returns, a development that banks are using to attract new deposits and retain existing ones.
Competitive Financing Offers Persist
Despite the rise in deposit rates, the increase has not uniformly affected loan interest rates. Banks continue to offer competitive financing deals to maintain their market share and attract new customers. A survey of major banks reveals that personal loan rates remain as low as 2.5%, with some institutions offering extended grace periods on repayments, ranging from three to twelve months.
Expert Insights on Interest Rate Dynamics
Ahmed Youssef, a banking expert, explains that the relationship between the base interest rate and loan pricing is complex. Factors such as the cost of funds, reference interest rates, loan types, and customer creditworthiness all influence bank pricing strategies. He emphasizes that, while deposit returns are increasing, the impact on loan rates is not immediate or uniform.
Savers Benefit in High-Interest Environments
Youssef highlights that the current high-interest environment favors savers, particularly those opting for fixed-term deposits. The return on these deposits varies between banks, depending on factors like deposit value, duration, and product terms. This variation presents savers with opportunities to maximize returns on their deposits.
Implications for Mortgage Borrowers
For mortgage borrowers, the effect of the interest rate hike depends on the nature of their financing. Fixed-interest loans remain unaffected during the fixed rate period, while variable-interest loans may see rate changes at the repricing date, contingent on the reference index specified in the contract.
Banking Competition Beyond Interest Rates
According to banker Tamer Abu Bakr, competition among banks extends beyond just interest rates. Factors such as fees, repayment periods, financing ratios, and conditions related to salary transfers also play crucial roles. As a result, customers may find significant differences in financing costs between banks, even when the base interest rate is consistent.
Future Outlook and Potential Adjustments
Abu Bakr anticipates that the effects of the interest rate hike will become more pronounced over time, especially with potential repricing of variable-interest loans. Banks are expected to continuously assess the cost of funds and adjust deposit returns, which may lead to further interest rate changes before year-end.
Balancing Act for Banks
The challenge for banks lies in maintaining a balance between offering competitive financing, attracting deposits, and managing funding costs. Higher interest rates tend to favor savers, but banks must carefully navigate these dynamics to sustain their financial stability and customer satisfaction.
